 Raul Delapena Setiawan
 Ammar Sabilarrohman
 Lina Irawan
 Suro Senen
In an era defined by rapid digital acceleration and the pervasive influence of artificial intelligence, a paradoxical shift is occurring in the British consumer landscape. Rather than retreating further into screens, the public is increasingly seeking refuge in the physical, the tangible, and the communal. This seismic change has birthed a flourishing "Experience Economy," a sector now serving as a vital engine for both cultural satisfaction and national economic growth.
A groundbreaking new study, the Experience Economy Index—produced by Grant Thornton UK in partnership with Experience UK and academic leads Dr. Hang-Yee Chan and Dr. Ozlem Tetik of King’s College London—has quantified this shift, revealing that the desire for escapism and shared human connection is fundamentally reshaping how the UK spends its money.
The Dawn of the Immersive Era
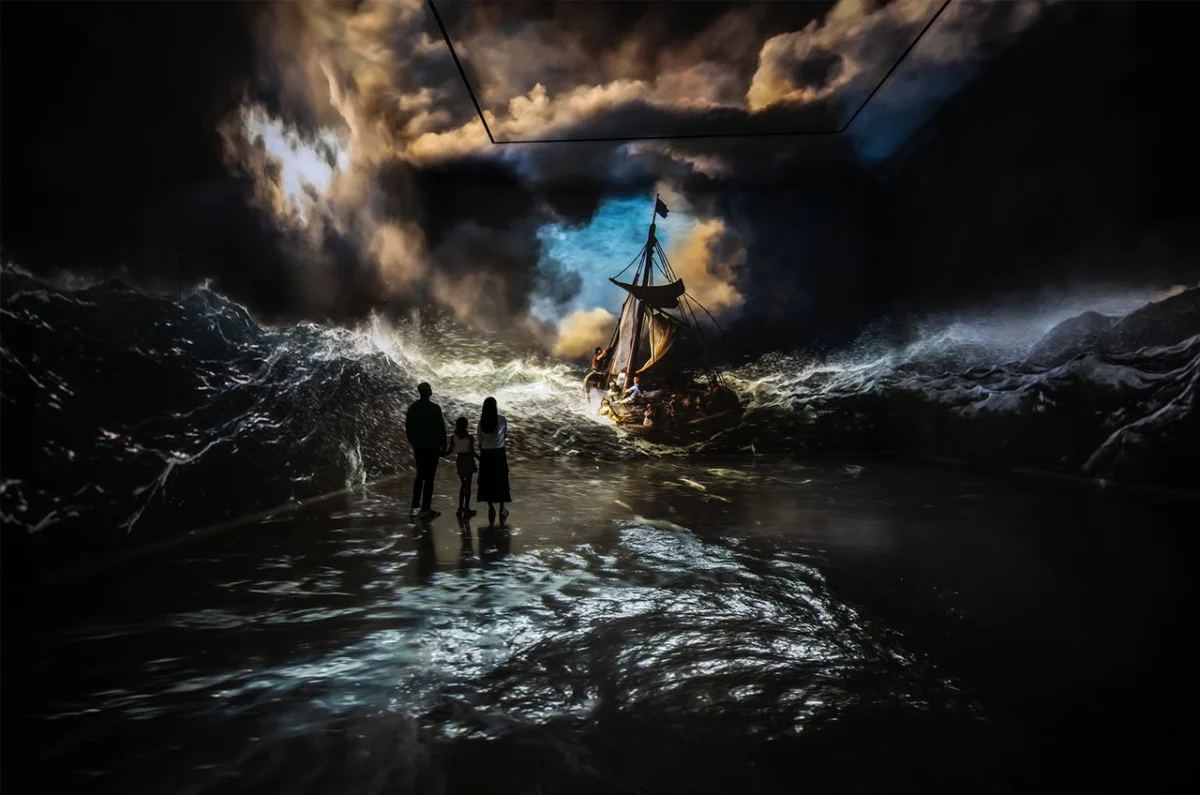
At the heart of this transformation is the rise of "immersion." Far from traditional passive consumption, immersive experiences invite audiences to become participants—moving through curated environments, interacting with narratives, and physically engaging with their surroundings.
From the high-tech, nostalgia-fueled spectacles of ABBA Voyage to the interactive puzzles of The Crystal Maze LIVE and the artistic wonder of Frameless, these ventures are no longer niche curiosities; they are significant economic contributors. According to the report, a staggering 31% of Britons—approximately 17 million adults—have attended an immersive experience within the last 12 months.
The economic footprint of this sub-sector is substantial. Grant Thornton’s modeling estimates that immersive experiences generated £7.4 billion in total spending over the past year. When accounting for supply chain activity and employee spending, this activity contributed £3.9 billion in Gross Value Added (GVA) to the UK economy and supported roughly 47,600 full-time equivalent jobs.
Chronology of a Cultural Shift
The transition toward an experience-based culture did not happen overnight, but it has gained significant momentum in the post-pandemic landscape.
- The Pre-Digital Baseline: Historically, consumerism was dominated by the accumulation of material goods. However, the early 2010s saw the beginning of a move toward "lifestyle" branding, where products were marketed as keys to experiences.
- The Pandemic Pivot: COVID-19 forced a total cessation of face-to-face interaction. The subsequent period of isolation acted as a pressure cooker, creating a "pent-up demand" for live events and shared physical space once restrictions were lifted.
- The AI Acceleration: As we moved into 2024 and 2025, the proliferation of generative AI and automated digital services prompted a "digital fatigue." The report identifies that 40% of UK adults now cite digital overload as a primary driver for seeking out physical experiences where they can feel "present."
- The Current Surge: 2025 data reveals that consumer spending in experience-related categories has reached at least £206 billion, accounting for 11.7% of total household expenditure. Researchers project this will climb to 13% by 2031, representing an additional £23 billion in current-day value.
Supporting Data: The Anatomy of Spending
The Experience Economy Index breaks down the financial behavior of the modern "experiencer." The average attendee spends roughly £210 per outing, a figure that includes more than just the price of a ticket.
Crucially, these events are acting as catalysts for regional economic regeneration. The report highlights that immersive experiences are not confined to London. They are delivering significant GVA to the regions, including £154 million in the North West, £233 million in Scotland, and £510 million in Northern Ireland.
The "ripple effect" of these events is profound for local hospitality and infrastructure:
- Hospitality: More than one-third of attendees dine or drink at local businesses near the venue.
- Retail: Nearly one-third take the opportunity to shop locally.
- Logistics: A quarter utilize local taxis or public transport, directly injecting funds into the local economy.
The psychological drivers behind this spending are equally clear. 38% of UK adults prioritize these events to create lasting memories, while 36% seek to improve the quality of time spent with loved ones. For the 18–34 age demographic, the shift is even more pronounced: 54% now explicitly state they prioritize experiences over material possessions.
Official Perspectives: The Experts Weigh In
Tom Middleton, Economic Consulting Partner at Grant Thornton UK, frames this development as a necessary correction to the digital age. "We’ve always loved a great experience—from Glastonbury and the theatre to visitor attractions and Oasis," Middleton notes. "But as AI and digital technology become an increasingly important part of how we live, work, and do business, the value of shared, in-person experiences is growing too."
Middleton emphasizes that the reach of this sector is broad, touching upon financial services, travel, retail, and infrastructure. It is not merely a segment of the entertainment industry; it is a horizontal force affecting the entire business ecosystem.
Dr. Hang-Yee Chan and Dr. Ozlem Tetik of King’s College London offer a more sociological perspective on why this trend is accelerating. They argue that the preference gap between "having" and "doing" is poised to widen as younger generations—who are inherently more experience-oriented—accrue greater spending power.
"Rising AI adoption may increase, rather than reduce, demand for face-to-face, human-mediated experiences," the professors state. "Live and shared moments gain relative value precisely because they cannot be automated. In an automated world, the ‘human touch’ becomes the ultimate luxury."
Implications for the Business Landscape
The report concludes with a clarion call to businesses across all sectors: the principles of the Experience Economy can—and should—be applied to traditional business models.
1. Moving Beyond the Transaction
For years, businesses focused on the "point of sale." The Experience Economy suggests that loyalty is no longer built on the product itself, but on the journey surrounding it. Companies that make their interactions more memorable, accessible, and connected are seeing higher customer retention.
2. The "Experience" as a Competitive Moat
Rob Turner, Consulting Partner at Grant Thornton UK, suggests that traditional retailers and service providers have much to learn from the immersive sector. "There is a lot that businesses can learn from the way the experience economy engages people," Turner explains. "For businesses, the opportunity is both to participate in the Experience Economy itself and to apply its lessons across the wider business ecosystem."
3. Regional Growth and Infrastructure
Policymakers should note the report’s findings regarding regional contribution. By incentivizing the creation of immersive hubs outside of the capital, local governments can stimulate local hospitality, retail, and transport sectors. The data suggests that a well-placed immersive venue functions as a "magnet," drawing visitors who spend significantly beyond the venue walls.
Conclusion: The Future is Physical
As we look toward 2031, the trajectory seems clear: the more digital our lives become, the more we will value the tangible, the communal, and the immersive. The Experience Economy is not a fleeting trend or a byproduct of post-lockdown enthusiasm; it is a fundamental recalibration of what consumers value most.
For businesses, the challenge is to pivot from being mere providers of goods to being architects of moments. For the UK economy, the opportunity lies in recognizing the Experience Economy as a vital pillar of future growth, capable of fostering innovation, creating thousands of jobs, and strengthening the social fabric of communities across the country. In a world of increasing automation, the most valuable commodity is, and will remain, the shared human experience.

 Dwi Wanna