 Azzam Bilal Chamdy
 Neng Nana
 Nana Muazin
 Dwi Wanna
 Raul Delapena Setiawan
 Laily UPN
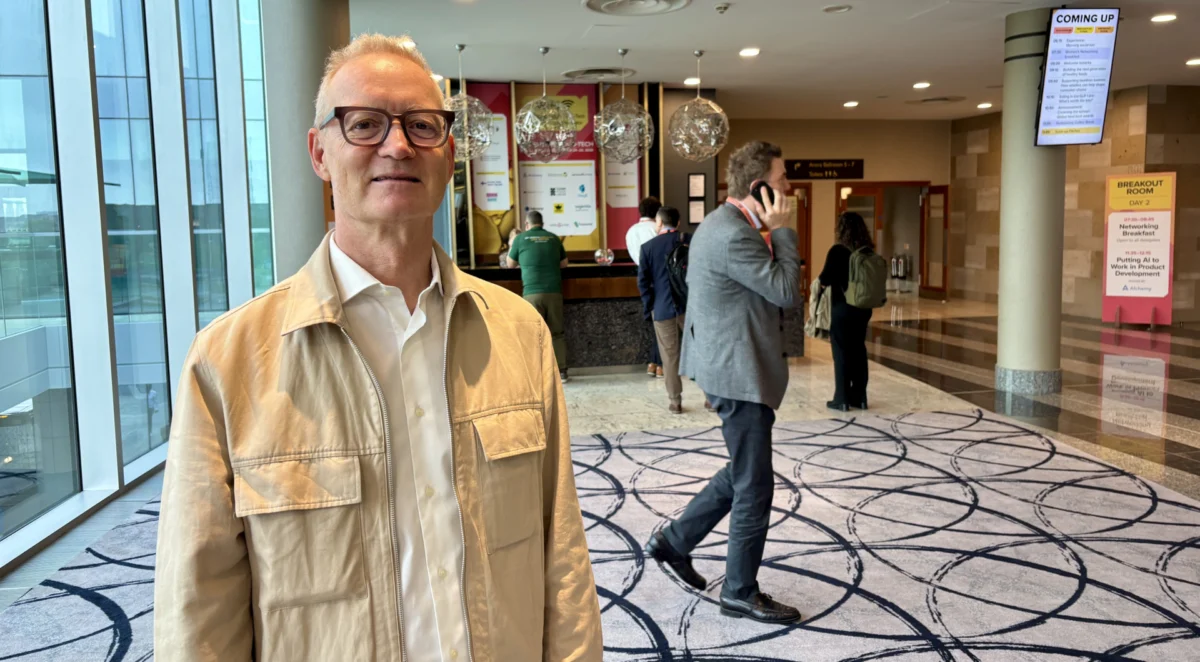
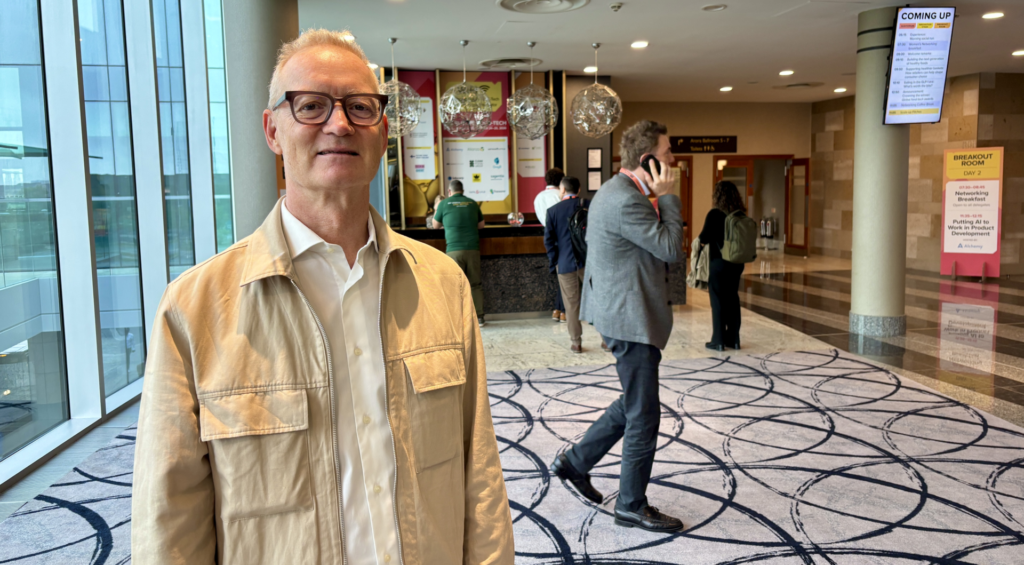
The global foodtech sector is currently emerging from a period of profound turbulence. Following a decade defined by the rapid rise and subsequent valuation correction of alternative proteins, the industry has hit a "reset" phase. According to Erich Sieber, founding general partner at Peakbridge, the sector has bottomed out, signaling that the time for strategic, evidence-based investment has returned.
Speaking at the Future Food-Tech summit in London, Sieber provided a roadmap for where the next wave of capital is flowing. As the market pivots away from high-capital, low-margin ventures, investors are increasingly drawn to the intersection of nutrition, clinical health, and artificial intelligence.
The Valuation Cycle: Where We Stand
A Market in Transition
The foodtech investment landscape has been characterized by "boom, bust, and reset." During the peak of the alternative protein hype, valuations were often decoupled from fundamental operational metrics. Today, the reality has set in. Sieber, who spent years managing a €750 million strategic venture fund at Nestlé, notes that the portfolio cycle has not yet caught up to the valuation cycle.
"I think we are at the bottom of the valuation cycle," Sieber explains. "However, regarding the funds themselves, we aren’t quite there yet. There will likely be more down rounds, restructuring, and liquidations before the sector fully stabilizes."
The Capital Efficiency Mandate
The primary lesson learned from the last five years is the distinction between capital-heavy and capital-efficient models. High-capex ventures—those requiring massive infrastructure to scale production—are facing significant headwinds. Conversely, startups that leverage existing supply chains or software-based platforms are finding a much warmer reception from limited partners (LPs).
Peakbridge, founded in 2019, has operated on a thesis that prioritizes "defensible" innovation. By focusing on five core pillars—functional ingredients, data/AI, nutrition and health, alternative proteins, and alternative farming—the firm has been able to pivot its capital allocation based on historical performance and market appetite.
Chronology of an Industry Pivot
The Early Days: Sustainability as a Driver
In the late 2010s, the investment thesis for foodtech was primarily centered on sustainability. The promise of reducing the carbon footprint of the food system drove massive amounts of capital into plant-based meat and cell-cultured agriculture. Consumers were viewed as moral agents who would shift their purchasing habits based on environmental impact.
The "Ultra-Processed" Backlash
The narrative shifted significantly when plant-based products faced scrutiny over their nutritional profiles. As critics labeled many alt-meat products as "ultra-processed," the initial consumer goodwill began to wane. Sieber argues that while sustainability was a popular buzzword, it never held the same long-term retention as health. "The consumer has always paid for health," he notes. "When you buy organic, you are buying health. The downfall of some plant-based brands was the discovery that they were not the nutritional panacea many expected."
The Current Era: Evidence-Based Intervention
Today, the industry is entering the era of "food as medicine." The focus has shifted from replacing animal products to optimizing human physiological outcomes. This evolution is marked by a reliance on clinical data, peer-reviewed studies, and integration with the traditional healthcare system.
Supporting Data: Why Nutrition and Health?
The GLP-1 Tsunami
The rise of GLP-1 receptor agonists (such as Ozempic and Wegovy) has fundamentally altered the food industry. These drugs, while effective for weight loss, create secondary challenges, including muscle loss and malnutrition. This has opened a multi-billion-dollar market for "wraparound" products.
Startups are now creating personalized nutrition platforms that assist patients in navigating these side effects. As Sieber points out, "Taking medicine is one thing, but managing the long-term lifestyle and nutritional maintenance is the real, profitable challenge."
The Women’s Health Gap
Women’s health represents a massive, historically underinvested segment of the market. With 50% of the population largely ignored by legacy food R&D, there is a clear opportunity to develop products for specific life stages—fertility, pregnancy, and menopause.
The strategy here is not to "pink-wash" existing products, but to provide functional, evidence-backed nutritional solutions that address specific hormonal and physiological needs. This segment is highly investable because it lacks the "fad" quality of previous food trends and aligns with long-term medical requirements.
Official Responses and Strategic Implications
The Exit Strategy: Pharma and Big Food
One of the most compelling aspects of the shift toward nutrition is the diversification of potential exit paths. Unlike pure-play foodtech, which relied on acquisitions by companies like Nestlé or Danone, the current landscape includes a wider pool of suitors.
Recent activity underscores this trend:
- Eli Lilly’s investment in Oura highlights the convergence of pharmaceutical interests with consumer health tracking.
- Unilever’s acquisition of Grüns and Danone’s acquisition of Huel demonstrate that traditional food giants are prioritizing "nutritionally superior" assets over generic food brands.
Sieber emphasizes that for a startup, being able to engage with both a pharma company and a food multinational creates a more liquid and higher-value exit landscape.
Closing the Loop with AI
AI is no longer a peripheral tool; it is the backbone of personalized nutrition. By analyzing blood markers, hormonal data, and biometric feedback, AI can provide granular, actionable advice that was previously the domain of expensive private clinics.
However, the value of AI in this space is not just in the software; it is in the "closing of the loop." Platforms like Ilant Health represent this new model: they do not just provide a product; they provide a service ecosystem that includes coaching, drug management, and nutritional support.
Implications for Public Health
The "Affluent vs. Accessible" Debate
A common critique of personalized nutrition is that it serves only the wealthy. Sieber addresses this by pointing toward the integration of foodtech into the broader healthcare system. "The goal is not to maximize the health of healthy people," he explains. "The goal is to reach those at risk of chronic disease."
The transition is occurring through regulatory and insurance-based channels. In the United States, health insurers are increasingly adopting codes for "preventative nutrition." Companies like NourishedRx exemplify this shift, where the insurer—not the individual—is the payer. As healthcare costs continue to skyrocket due to aging populations, the economic argument for prevention is becoming impossible to ignore.
The Path Forward
For founders and investors, the message is clear: the era of "growth at any cost" is over. The next successful foodtech companies will be those that:
- Prioritize clinical validation: Every health claim must be backed by data that can withstand the scrutiny of a physician.
- Integrate with healthcare: Align with insurers and medical providers to ensure access and payment.
- Utilize AI for personalization: Move beyond one-size-fits-all products to solutions tailored to individual biomarkers.
"We shouldn’t forget that healthcare costs are ballooning," Sieber concludes. "With the current demographics of fewer children and people living longer, prevention is the only way to reduce the systemic burden on our health infrastructure. That is where the real value—and the real investment opportunity—lies."
As the sector moves forward, the "reset" is likely to produce a more mature, resilient, and scientifically rigorous industry. The bubble may have burst, but the underlying mission—to improve human health through better nutrition—has never been more commercially viable.

 Rifan Muazin